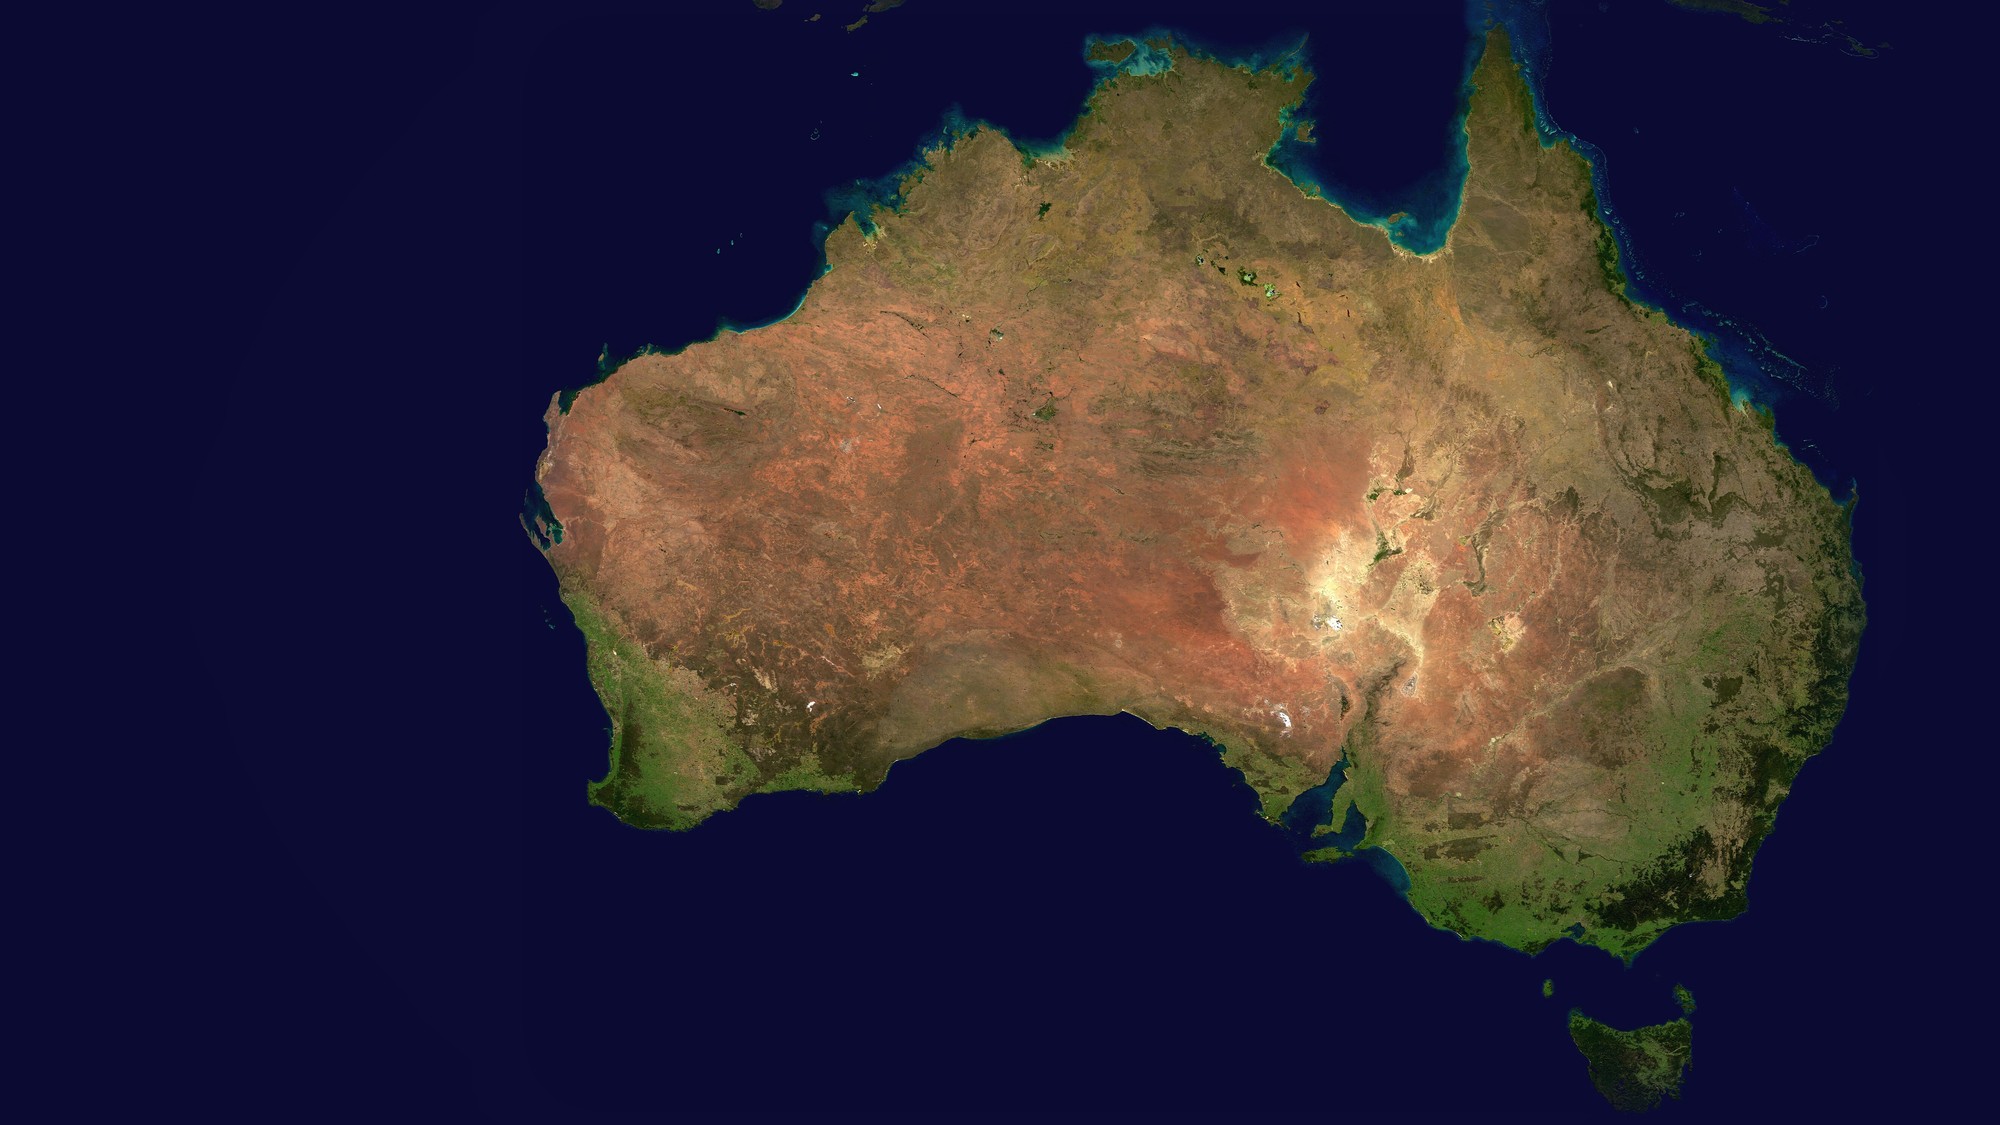
Ask me where the best rental yields in Australia are and I can tell you. We've ranked every state, houses and units, on what places actually sold for against what they actually rent for. But the number everyone chases isn't the number that makes you money, and that's worth understanding before you scroll.
What a rental yield actually is
Plenty of people have never had this explained to them properly, and there's no reason they should have. So before anything else, here it is.
A rental yield is the rent a property brings in, expressed as a percentage of what the property cost. That's all it is.
Every figure on this page is a gross yield, which means rent against price and nothing taken off. Rates, insurance, property management, maintenance and the weeks it sits empty usually account for 20 to 25 percent of the rent before you've paid a cent of the loan. So that 5.2 percent is closer to 4 percent by the time the property is actually running.
Why the yield matters
A property costs money to own. Rates, insurance, management, repairs, and the loan. The yield is what tells you how much of that the tenant is covering.
A high yield means the rent does most of the heavy lifting and the property costs you little to keep. A low yield means you're topping it up out of your own pocket every month, sometimes for years.
That's the whole job of the number. It isn't a measure of how good an investment is. It's a measure of how comfortable the property will be to hold, and that turns out to matter more than most people expect. We'll come back to why at the end.
Where the national numbers sit right now
Cotality has the national gross yield at 3.85 percent, the highest it's been since August 2019. Across the capitals it runs from 3.4 percent in Sydney to 6.5 percent in Darwin.
Yields are repairing because rents kept climbing while values eased. That's the first time in years the arithmetic has moved in a buyer's favour, and it's the reason this is worth looking at now rather than two years ago.
But a national average across roughly fifteen thousand suburbs describes almost none of them. So we went underneath it.
What a yield has to clear before it pays for itself
A percentage on its own means nothing until you know what it has to beat.
With investment loans sitting around 6.5 percent, and roughly a fifth to a quarter of the rent disappearing into costs, a property lands somewhere near breaking even at about a 7 percent gross yield. Above that, the rent is carrying the property. Below it, you are.
That one line explains why the lists below look the way they do. Very few Australian suburbs clear 7 percent, and the ones that do are mostly a long way from a capital city.
The highest yields in every state
Two lists per state. The top ten on gross yield, and then the one most people are actually after, the strongest yields you can still buy under $800,000.
New South Wales
Top 10 by gross rental yield · 6 of 10 are units
Victoria
Top 10 by gross rental yield · 7 of 10 are units
Queensland
Top 10 by gross rental yield · 7 of 10 are units
South Australia
Top 10 by gross rental yield · 7 of 10 are units
Western Australia
Top 10 by gross rental yield · 7 of 10 are units
Tasmania
Top 10 by gross rental yield · 7 of 10 are units
Northern Territory
Top 10 by gross rental yield · 6 of 10 are units
ACT
Top 10 by gross rental yield · 10 of 10 are units
What the lists show
Units dominate. Ten out of ten in the ACT. Seven out of ten in Victoria, Queensland, South Australia, Western Australia and Tasmania.
That's not a quirk. A unit costs less to buy but rents for a surprisingly similar amount to a house in the same suburb, because tenants pay for location and bedrooms rather than for land. Take the land out of the price and the percentage goes up.
Canberra shows it cleanly. Houses there top out around 4.8 percent. Units in Curtin and Lyons run 7.13 and 6.74 percent on medians near $350,000. Same city, same tenants, nearly three points apart.
Read the top of these lists carefully
Two things run through the strongest numbers, and both matter.
Resources towns. Look at Western Australia and South Australia. Boulder, South Kalgoorlie, Kalgoorlie, Bulgarra and Millars Well in the Pilbara. Whyalla and Roxby Downs. These yields are real and they're genuinely paid. They're also paid by one industry. A single mine's roster decision can move the rent, the vacancy rate and the price together, in the same quarter, in the same direction. That's a very different proposition to a suburb where the tenants work across a dozen industries.
Thin markets. The smaller the town, the fewer the buyers on the day you want out. A 9 percent yield in a place that trades thirty houses a year is a different asset to a 5 percent yield twenty minutes from a capital, even though a list puts them in the same column.
The Northern Territory sits in the same conversation for a different reason. Darwin looks strong on current yield because prices there are low, and prices are low because the market has gone close to nowhere for a decade. Cotality has Darwin up 33.8 percent over ten years against Brisbane on 105.3, Adelaide on 104.3 and Perth on 97.6. A good yield on a value that hasn't moved in ten years is an income return and not much else. Go in knowing which of the two you're buying.
Now the part that actually makes the money
Here's what I'd want you to take away, and it's the opposite of what an article ranking yields usually says.
The yield is not where the money is. Capital growth is. And growth works on the whole value of the property, not on the slice of it you paid for.
Cotality Home Value Index, ten years to 30 September 2026. Past performance is not a forecast, and the spread is enormous: over that same decade Melbourne rose 24.3 percent while Brisbane rose 105.3 percent.
That spread is the honest part of this. Growth is where the money is, and growth is the part nobody can promise you. Brisbane did 105 percent over that decade. Melbourne did 24. Same country, same ten years. Different markets cycle at different times, which is why the state you buy in matters as much as the year you buy in.
Which is exactly why time in the market beats timing the market. You can't pick the quarter a market turns, and the people who try usually sit out the years that did the work. What history keeps showing is that the longer the hold, the less the entry point matters.
The yield isn't the return. It's what lets you hold the asset to get the bigger gain, the capital growth. A property you can comfortably hold for fifteen years will almost always beat a better property you were forced to sell in year four.
So you need a yield you can live with, in a market worth being in
That's the tension this whole article sits on. The best growth markets tend to have the worst yields, and the best yields tend to sit in towns you wouldn't want to be stuck in for fifteen years.
Chasing the percentage by postcode forces that trade. It sends you to a mining town or a market of two thousand people to find a number that lets you hold on.
There's another way to get there, and it's the one we spend our time on. The yield isn't only a function of where you buy. It's a function of what you build and how it's configured. The same block, in the same suburb, can produce very different income depending on what goes on it.
A second dwelling
A granny flat or secondary dwelling puts a second rent on a single title. One block, one set of rates, two incomes.
Dual key
One roofline, two self-contained sides with their own entries. Rents as two. Valued as one home.
Dual occupancy
Two dwellings on one block. Not investor-only either. Plenty of people live in one side while the other pays the loan down.
Co-living and rooming
Rooms let individually instead of the house let once. Higher gross income, run by specialist managers rather than by you, and it falls back to an ordinary house whenever you want it to.
Duplex
Two dwellings, two titles. Hold both for two incomes, or sell one and hold the other.
Every one of those lifts the income side of the equation rather than cutting the price side. Which means you don't have to accept a 3.4 percent Sydney yield, and you don't have to move your money to Mount Isa to escape it. You can buy in a market with more than one employer, more than one reason for people to live there, and a decade of growth behind it, and still build something that pays enough rent to let you hold it.
That's the job. Not finding the biggest number on a list. Finding a property you can still comfortably own in fifteen years, in a place worth owning it.
Common questions
What is a rental yield and how do you calculate it?
What is a good rental yield in Australia in 2026?
Which Australian suburbs have the highest rental yields?
Do units have better rental yields than houses?
Is rental yield or capital growth more important?
How do you improve rental yield without buying in a mining town?
- What places actually sold for, not what they were advertised at. An asking price is a hope. A sale price is what somebody paid.
- Real rents, from bond records where we could get them. When a tenant pays a bond it gets lodged with the state, so those figures come off signed leases rather than off a listing.
- Only towns of 2,000 people or more. A median price is only as good as the number of sales behind it. In a town of three hundred people that might be four sales in a whole year, which tells you next to nothing and leaves you with almost no buyers on the day you want to sell.
- If the rent and the price didn't agree, we binned it. Anything producing a figure the Census couldn't back up came off the list instead of going on the page.
We started with 14,836 suburbs. 7,677 had a sold median we could stand behind. 4,817 of those also had a rent to pair it with. The population floor and the quality checks took it to 2,127 suburbs, across houses and units. The rest were dropped because the data wasn't good enough to publish, not because the suburbs don't exist.
Sources
- Cotality, Home Value Index and monthly chart pack, 30 September 2026 (national and capital city gross yields, ten year capital growth by capital)
- Suburb sold medians to September and October 2026, compiled from realestate.com.au, REIWA, OnTheHouse, Heatmaps, property.com.au, Domain and state Valuer-General releases
- Residential Tenancies Authority Queensland bond lodgements (CC BY 3.0 AU)
- NSW Fair Trading bond lodgement data
- Homes Victoria rental report (CC BY 4.0)
- South Australian Housing Trust bond data (CC BY 4.0)
- Australian Bureau of Statistics, Census 2021 (population and median weekly rent)
- Reserve Bank of Australia, Cash Rate Target, 4.60 percent effective 30 September 2026